Wild Fortune Withdrawal Australia: Limits, Timing, Fees and KYC
 Available in US
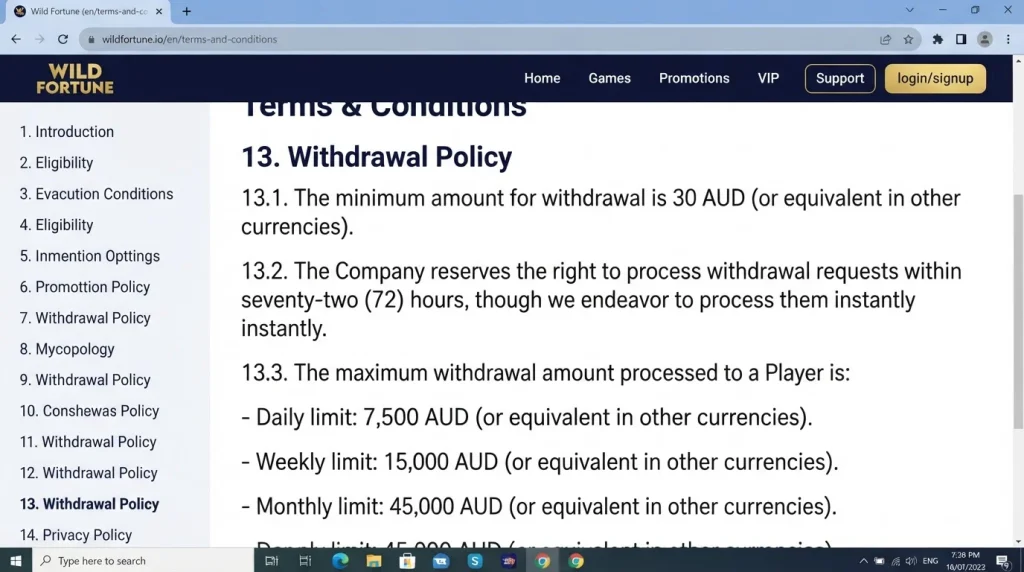
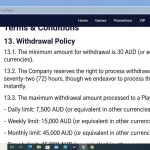
For Australian-dollar withdrawals, Wild Fortune’s current official terms set a minimum cashout of AU$30 and frequency limits of AU$1,500 per day, AU$7,500 over a rolling seven-day period and AU$22,500 per month. The operator says it aims to process withdrawal requests within 72 hours of approval. That is an operator-processing target, not a promise that money will reach a bank account or card within 72 hours. Verification status, the selected payment route and the payment provider can all affect the point at which funds actually arrive.
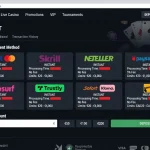
The practical way to judge a Wild Fortune withdrawal is to separate four stages: whether the account is eligible to cash out, whether KYC is complete, how long Wild Fortune takes to approve and process the request, and how long the receiving bank, card network, e-wallet or crypto network then takes. The wider payment methods guide covers banking options, while this page concentrates on the rules that directly affect cashing out.
Table of Contents
- Current AUD withdrawal limits at a glance
- Processing time is not the same as settlement time
- KYC can pause a withdrawal
- Payment routing can change the way a cashout arrives
- Fees: distinguish operator rules from bank charges
- How the frequency limits work in practice
- Pre-withdrawal checklist
- What to do when a withdrawal is delayed
- Current rules versus stale search-result figures
- Two cashout scenarios that are easy to misread
- Withdrawal FAQ
- Wild Fortune Payment Methods Australia: Deposits, Crypto and Cashier Guide
Current AUD withdrawal limits at a glance
| Rule | Current official value | What it means |
|---|---|---|
| Minimum fiat withdrawal | AU$30 | A fiat cashout below this amount does not meet the published AUD minimum. |
| Daily frequency limit | AU$1,500 | The standard daily withdrawal ceiling stated for AUD. |
| Weekly limit | AU$7,500 | Applied on a rolling seven-day basis. |
| Monthly limit | AU$22,500 | The stated monthly ceiling for AUD, with the terms noting a reset on the first of each month. |
| Operator processing target | Within 72 hours of approval | This covers Wild Fortune’s processing target after approval, not final settlement by the receiving provider. |
Withdrawal limits and processing terms can change, so check the current casino terms and cashier before requesting a withdrawal.
Processing time is not the same as settlement time
The phrase “within 72 hours of approval” describes the operator’s processing target. It does not mean every player receives money exactly three days after clicking withdraw. A request first has to pass the account and transaction checks that apply to it. Only after approval does the stated processing target begin to make sense as a useful benchmark.
After Wild Fortune sends the payment onward, a separate settlement period can apply. The terms state that bank transfers are processed within three business days, while also warning that banks can reject or delay transfers. Card payouts can use Visa Original Credit Transfer or Mastercard Payment Transfer where supported, and the issuing bank still has discretion over acceptance. This is why a casino-side status such as approved or processed should not be confused with cleared funds in the receiving account.
For a cleaner comparison, track three timestamps: when the withdrawal was requested, when it was approved, and when Wild Fortune marked it processed. If the payment then remains outstanding, the useful question for support is whether the operator has released the funds and whether a transaction reference is available. The support and disputes guide explains escalation in more detail.
KYC can pause a withdrawal
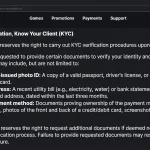
Wild Fortune reserves the right to verify identity before processing withdrawals. The current terms list government-issued photo ID and proof of address as core identification material and allow additional documentation to confirm identity or the payment method. Elsewhere in the KYC section, the terms also describe proof of payment method as a possible requirement. This makes verification a real part of the withdrawal process rather than a separate administrative topic.
A useful distinction is that the terms define document categories but do not provide one universal verification turnaround that applies to every account. It would therefore be misleading to promise that KYC takes a fixed number of hours. A request can remain pending while verification is incomplete, and false or incomplete documents can lead to refusal of a payout or account action.
Before a significant cashout, check that the legal name, address information and payment details are internally consistent. Keep clear copies of current documents available, and respond to verification requests through the account or official support route. For the document rules and verification logic in one place, use the KYC requirements guide.
Payment routing can change the way a cashout arrives
The requested withdrawal method is not always the final route. Wild Fortune’s terms reserve the right to pay by a different method when necessary. For card-funded accounts, the operator can return an amount up to the net card deposit back to that card and route any excess through an alternative method such as an e-wallet or bank transfer. That can make a single balance appear as more than one payment path.
The same-name principle matters before withdrawal. The deposit rules require funds to come from a payment account registered in the player’s own name. Using someone else’s bank account, card or e-wallet creates a preventable verification and ownership problem. If a first deposit has not yet been made, the deposit guide explains why matching account-holder details from the beginning is the safer approach.
Fees: distinguish operator rules from bank charges
Wild Fortune’s terms place responsibility for bank or payment-provider fees on the player. They also state that intermediary banks can impose charges on bank transfers. Because those costs come from third parties and can depend on the route, there is no reliable basis for presenting one universal AUD withdrawal fee across every method.
That distinction matters when comparing cashier screens. A method can show no operator fee yet still involve charges imposed by a receiving bank, intermediary bank, card issuer or wallet provider. Check the cashier before confirming the request and, for a bank transfer, consider whether the receiving institution has incoming-transfer fees.
How the frequency limits work in practice
The AU$1,500 daily, AU$7,500 weekly and AU$22,500 monthly figures are frequency limits rather than a statement that every method can handle those amounts in one transaction. The terms separately say the maximum amount can vary by payment method and that the exact method limit is shown during withdrawal. If a requested amount exceeds a method’s limit, payouts can be divided into instalments.
The weekly figure is described as rolling seven days, while the monthly limit resets on the first day of the month. That difference is easy to miss. A rolling weekly window follows the previous seven days rather than a simple Monday-to-Sunday calendar. A player making several withdrawals close together should therefore look at recent cashouts, not just the current calendar week.
The terms also say higher VIP levels can receive changed withdrawal limits at the casino’s discretion. Treat the cashier and account-specific communication as the operational source for any personalised limit rather than assuming the standard table applies unchanged to every account.
Pre-withdrawal checklist
- Confirm the requested amount is at least AU$30.
- Check recent withdrawals against the AU$1,500 daily, AU$7,500 rolling-weekly and AU$22,500 monthly standard limits.
- Make sure the account holder name and the payment method ownership match.
- Complete any requested identity, address or payment-method verification before expecting processing to finish.
- Check the cashier for the current method-specific maximum and available withdrawal route.
- Record the request and approval timestamps so the 72-hour processing target is measured from approval, not from the first click.
- If the operator marks the payment processed but it has not arrived, ask support for the payment route and any available transaction reference.
This checklist avoids the most common timing mistake: treating every delay as casino processing. The account, KYC, operator-processing and provider-settlement stages should be checked separately.
What to do when a withdrawal is delayed
Start with the account status. If verification is outstanding, complete that first because the terms explicitly allow withdrawals to remain pending while required checks are incomplete. If verification is complete, compare the elapsed time with the point of approval rather than the original request time.
Next, confirm the method. A bank transfer, card payout, e-wallet payment and crypto transaction do not share the same downstream settlement mechanics. If Wild Fortune has already processed the request, check the status with the receiving payment provider.
When contacting support, provide the withdrawal amount, request date, approval date if shown, payment method and current status. Avoid sending sensitive document images through an unconfirmed channel. The AU pages describe live chat and email support, so use the official site routes for account-specific cases.
Current rules versus stale search-result figures
Withdrawal limits and processing times can change. Check the current AUD terms and cashier before submitting a request.
Check the exact value in the current terms or cashier before submitting a withdrawal, as account- and method-specific limits can change.
Two cashout scenarios that are easy to misread
Consider a withdrawal requested late on a Friday. The request time alone does not establish when the operator’s 72-hour target should be measured, because the published wording is tied to approval. If the account enters verification first, the more useful timeline begins with the completion of the checks and the subsequent approval status. Keeping dated account records of those status changes can make a support conversation much more precise.
A second common scenario is a larger balance that has to be paid in more than one instalment. The standard AUD frequency limits and any method-specific maximum can both influence how a payout is divided. Multiple payments therefore do not automatically indicate an error. Compare each instalment with the cashier limit, the standard daily/weekly/monthly rules and any account-specific notice before escalating.
Withdrawal FAQ
What is the minimum Wild Fortune withdrawal in AUD?
The current official terms list AU$30 as the minimum fiat withdrawal for AUD.
Does Wild Fortune guarantee a payout within 72 hours?
No. The terms say Wild Fortune aims to process withdrawal requests within 72 hours of approval. Verification and payment-provider settlement can extend the total time before funds arrive.
What are the standard AUD withdrawal limits?
The current terms state AU$1,500 daily, AU$7,500 over a rolling seven-day period and AU$22,500 monthly.
Can KYC be requested before withdrawal?
Yes. The terms allow Wild Fortune to verify identity before processing withdrawals and list identity, address and payment-method information among the documents that can be requested.
For the broader Australian assessment, including games, bonuses, account setup and regulatory context, return to the Wild Fortune Australia guide.